Every investor eventually asks the same impossible question: “How do I get stock market returns without stock market risk?”
It is a completely rational desire. Nobody enjoys watching their portfolio drop 20% during a bear market. We all want the upside of equities combined with the safety of a bank account.
Wall Street knows this. In fact, the financial industry spends billions of dollars manufacturing and marketing products designed to appeal exactly to this desire. The pitch usually revolves around “downside protection,” “defined outcomes,” or “buffered growth.”
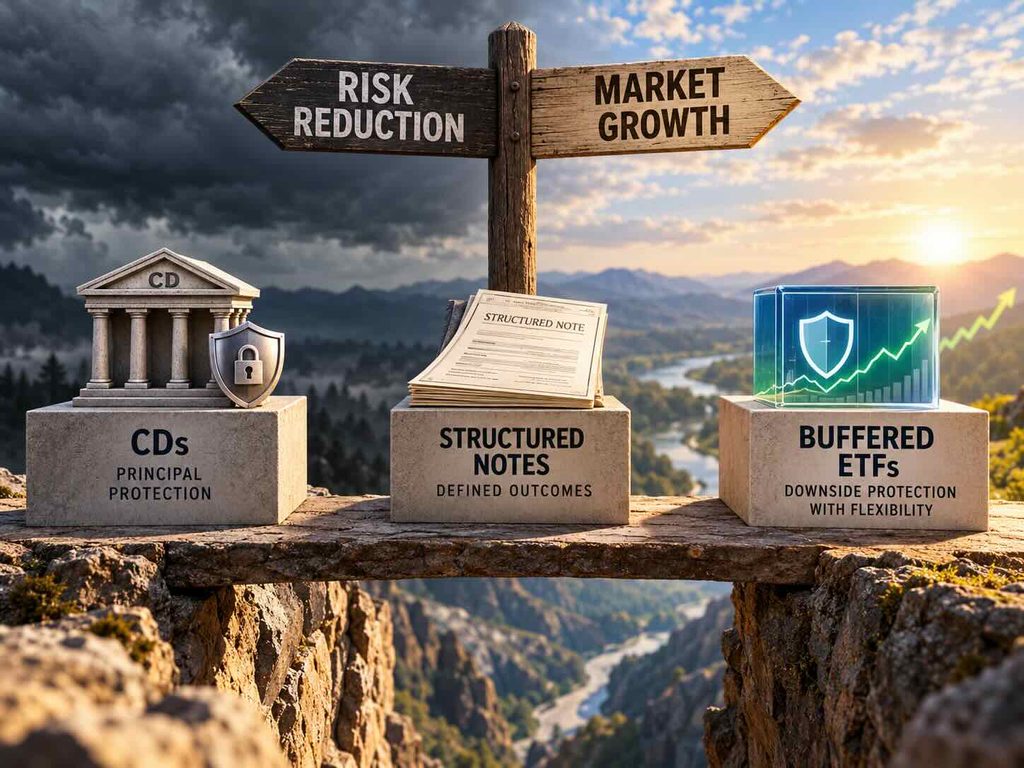
Today, that conversation generally centers around three distinct tools: Certificates of Deposit (CDs), Structured Notes, and Buffered ETFs.
They all promise a smoother ride. But just like Medicaid planning or borrowing against a portfolio, there is always a trade-off. In the financial markets, you cannot eliminate risk; you can only trade one type of risk for another. The question is whether you understand what you are buying, what you are giving up, and whether the trade is actually worth it.
The Baseline: Certificates of Deposit (CDs)
Let’s start with the most familiar option. A CD is a straightforward proposition: you lend a bank your money for a set period, and they guarantee your principal plus a fixed interest rate, backed by FDIC insurance up to applicable limits.
When interest rates are relatively high, CDs look incredibly attractive. You get absolute principal protection and a known return.
The Trade-Off:
With a CD, you are trading market risk for inflation risk and opportunity cost. Your principal is safe, but if inflation runs higher than your after-tax interest rate, your actual purchasing power is shrinking. Furthermore, you have completely surrendered any participation in economic growth. If the stock market rallies 25% while your money is locked in a 12-month CD, you miss that growth entirely.
CDs are excellent for cash you know you will need in the short term. They are generally terrible vehicles for long-term wealth creation.
The Pitch: Structured Notes
Because investors hate giving up all the market upside just to stay safe, the industry created Structured Notes. These are complex financial instruments, heavily pushed by major banks and brokerages, that sound almost too good to be true.
A typical pitch for a buffered structured note sounds like this: “You participate in the upside of the S&P 500 up to a 10% cap, but we protect you against the first 15% of market losses.”
If the market drops 10%, you lose nothing. If it drops 20%, you only lose 5%. If it goes up 15%, you get 10%. It sounds like the perfect middle ground.
But what is a structured note, exactly?
It is not a mutual fund or a direct investment in the stock market. A structured note is an unsecured debt obligation of the bank issuing it, combined with a package of derivative options.
The Trade-Off:
Structured notes carry several massive hidden costs:
- Credit Risk: Because a note is essentially a loan to a bank, your “guaranteed” protection is only as strong as the bank’s balance sheet. If the issuing bank goes bankrupt (as Lehman Brothers did in 2008), your downside protection vanishes, and you become an unsecured creditor.
- Absolute Illiquidity: Structured notes are designed to be held to maturity (often 2 to 5 years). There is usually no active secondary market. If you need your money early, the bank might offer to buy it back, but usually at a severe penalty.
- Opaque Pricing and Fees: The fees are baked into the complex options pricing structure. You rarely see a line item for the fee, making it incredibly difficult to know how much the bank is actually charging you to manufacture the product.
- Capped Upside: You are giving away the best market days. Historically, the stock market generates a large portion of its long-term returns in a handful of massive, double-digit years. By capping your upside, you severely stunt long-term compounding.
The Evolution: Buffered ETFs
In recent years, the industry recognized that investors disliked the illiquidity, credit risk, and opacity of structured notes. The solution was the Buffered ETF (often called Defined Outcome ETFs).
Buffered ETFs take the same basic economic strategy—using options to create a floor on losses and a cap on gains—and place it inside a traditional ETF structure.
This solves several of the major problems associated with structured notes. You do not have the credit risk of a single bank failing. You have daily liquidity, meaning you can buy or sell the ETF on the open market whenever you want. The fees are transparent and stated as a standard expense ratio.
They are generally a massive improvement over traditional structured notes. But they still require a careful look under the hood.
The Trade-Off:
While Buffered ETFs fix the liquidity and credit problems, they introduce a new mechanical quirk: The math only works perfectly if you hold the ETF for its exact “outcome period.”
Buffered ETFs are typically designed on a one-year cycle (e.g., January 1st to December 31st). If the ETF promises a 15% buffer and a 12% cap, those numbers only apply if you buy on day one and hold until the final day of the cycle.
If you buy into the ETF three months later, the market has already moved. If the market is already up 8%, your remaining upside before hitting the cap is much smaller, and your downside buffer is shifted. The ETF providers publish these daily shifting metrics, but it forces the investor to carefully track the exact entry and exit math.
Furthermore, just like structured notes, you are still permanently capping your upside. You are trading away your highest returning years in exchange for a smoother ride.
The Real Cost of a Floor
Whether you use a Structured Note or a Buffered ETF, the underlying mechanics are the same. The product manufacturer is buying a “put” option to protect your downside, and they are paying for it by selling a “call” option that caps your upside.
There is no magic. Downside protection is expensive. You pay for the floor by selling the ceiling.
This isn’t inherently wrong. There are absolutely times when an investor may want to define their outcomes, limit their volatility, and accept a lower maximum return.
But investors often buy these products because they are afraid of a market crash, without realizing they are virtually guaranteeing they will underperform a simple index fund over a 10- or 20-year horizon.
Aligning the Tool With the Goal
The financial industry loves to sell products. Financial planning is about determining if you actually need the product in the first place.
If you need absolute safety for a down payment on a house in six months, a CD or a Treasury bill does the job perfectly.
If you have a 20-year time horizon and don’t need the capital anytime soon, permanently capping your upside with a Buffered ETF or a Structured Note is often a mathematical mistake, no matter how comforting the downside protection feels today. Volatility is simply the price of admission for long-term equity returns.
Buffered products tend to make the most sense for a very specific type of investor in a very specific window of time—such as a retiree in their first few years of drawing down their portfolio, who wants to stay invested in equities but absolutely cannot afford a 25% sequence-of-returns shock.
The question isn’t whether CDs, Notes, or Buffered ETFs are “good” or “bad.” The question is what specific risk you are trying to mitigate, and whether you are willing to pay the required cost to mitigate it.