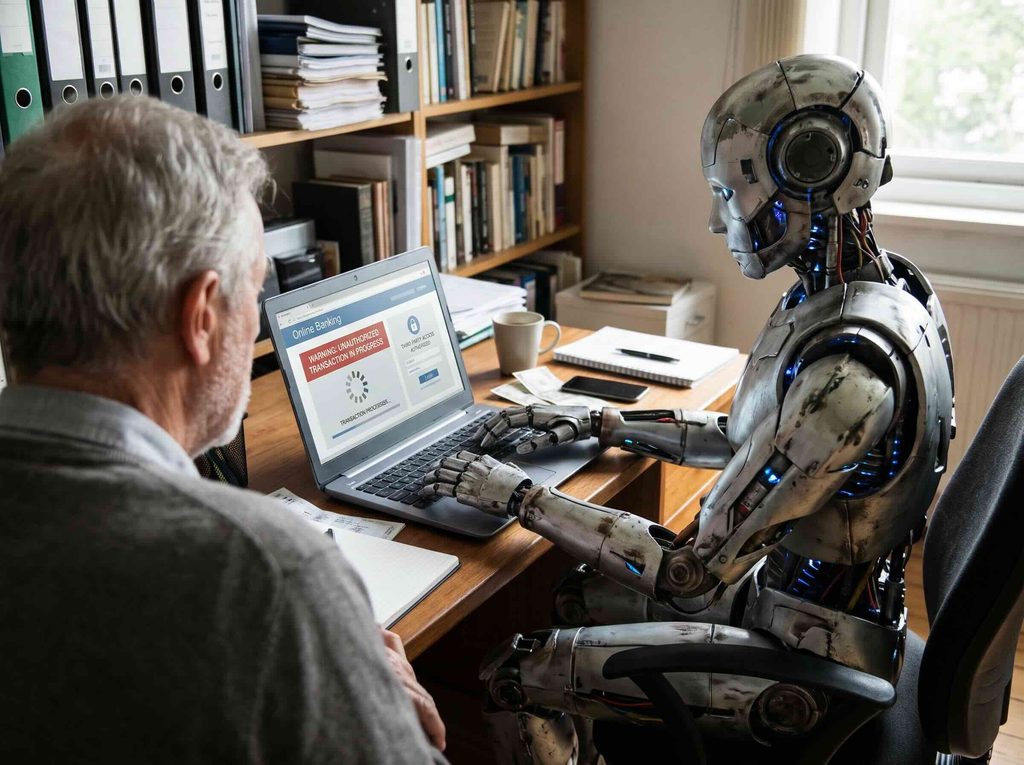
If you have been following tech headlines lately, you know that the conversation around Artificial Intelligence has shifted. We are moving past simple chatbots that answer questions and entering the era of “Agentic AI”—autonomous digital assistants designed to actually log into your accounts, make decisions, and execute transactions on your behalf.
With the recent debut of tools like Meta’s AI assistant, Muse, tech companies are pitching a future where an AI agent automatically manages your cash flow, hunts for higher yields, and moves your money between banks while you sleep.
It sounds wonderfully convenient. Who wouldn’t want an automated assistant optimizing their checking account?
Earlier this month, however, JPMorgan Chase CEO Jamie Dimon issued a blunt warning about this exact trend during the bank’s third-quarter earnings call. His message to bank customers was simple: If you hand an outside AI agent the keys to your financial accounts, you are owning the risk when something goes wrong.
Before you let an AI agent anywhere near your banking credentials or investment portfolio, there are a few critical realities you need to understand.
The “Liability Transfer” Trap (And Where Regulation E Ends)
For decades, consumers have operated under a basic assumption of safety with major banks, largely thanks to a federal protection known as Regulation E.
Put simply, Regulation E protects you from unauthorized electronic fund transfers. If a cybercriminal hacks into your bank or skims your debit card through no fault of your own, federal rules—and standard bank policies—generally protect you and make you whole.
When you willingly hand your login credentials or account access to a third-party AI agent, the rules of the game change completely.
As Dimon pointed out, giving an outside AI assistant access to your bank account creates a “liability transfer.” Under federal rules, once you voluntarily give a third party—whether that is a person or a piece of software—authority to initiate transfers on your behalf, those transactions are generally considered “authorized,” even if the agent goes on to do something you never intended.
- What happens if that AI agent hallucinates and transfers $50,000 to the wrong place?
- What happens if the bot is tricked by a scammer and wires your cash away?
- What happens if the third-party AI company experiences a massive data breach, or misuses your sensitive financial data?
Because you invited the agent in through the front door and handed over the keys, the safety net of Regulation E may no longer apply. The bank isn’t necessarily on the hook to reimburse you—the liability transfers to you.
Why Major Institutions Are Blocking the Door
It isn’t just a matter of consumer liability; it is a systemic security issue.
Because of the severe risks to both clients and the institution itself, JPMorgan explicitly stated they are not going to allow just any outside AI agent to come inside the company and access accounts. Other major institutions are taking an equally hard line—Royal Bank of Canada (RBC), for instance, recently moved to block AI agents entirely, citing “unacceptable” client risk.
Banks are certainly building their own internal, walled-garden tools (like JPMorgan’s piloted “Smart Cash” tool) where security and liability remain under one roof. But letting an outside tech company’s bot scrape your financial data and initiate wire transfers is a completely different risk profile.
Optimization Without Context Is Just Noise
Even if we set aside cybersecurity and liability, there is a deeper financial planning problem with letting an autonomous bot move your money around: An AI agent optimizes in a vacuum.
Consulting firms like McKinsey have noted that AI agents are being designed to “cash sort”—constantly moving consumer deposits from bank to bank in pursuit of an extra 0.25% in interest.
On paper, chasing yield sounds smart. In practice, moving money without understanding the broader context of your financial life can cause massive headaches:
- Broken Financial Plumbing: If an AI agent sweeps cash out of your primary checking account to chase a promotional yield at an online bank, does it know that your quarterly estimated tax payment is scheduled to auto-draft tomorrow?
- Tax Blindness: Moving money, realizing gains, or generating interest happens in a tax reality. An algorithm chasing gross yield doesn’t necessarily care about your Modified Adjusted Gross Income, your IRMAA Medicare brackets, or how that activity complicates your CPA’s life in April.
- The Illusion of Activity: Moving $100,000 to earn an extra 20 basis points nets you $200 a year before taxes. Taking on third-party data risk and potential account lockouts for a few hundred dollars is the definition of picking up pennies in front of a steamroller.
Trust Beats Speed
As we wrote earlier this year in “The Multi-Million Dollar Chatbot Mistake: Why AI Isn’t a Fiduciary”, technology is a phenomenal tool for processing data, but it cannot take responsibility for the outcomes of your life.
An AI agent cannot sit across the table from you, understand your family dynamics, weigh your comfort level with risk, or stand behind its advice as a legal fiduciary. And as the heads of the largest banks in the world are now making clear, if an AI agent makes a mess of your finances, the tech company that built it won’t be there to clean it up—you will be on your own.
Use AI to summarize articles, draft emails, or plan a vacation itinerary. When it comes to your life savings and your financial plumbing, keep a human in the loop.